The 30-Day Free Look Period for Burial Insurance Explained
Test-drive your final expense policy with zero financial risk using state-mandated free look laws to ensure you have the right coverage.
The short answer
The 30-day free look period is a legally mandated window that allows you to cancel a new life insurance policy for any reason and receive a 100% full refund. The countdown begins on the exact day your policy is delivered, giving you time to review the terms without financial risk.
- The free look clock starts on the day your policy is delivered to you, not on the day you apply or pay your first premium.
- State laws mandate a 10 to 30 day window to cancel your policy for a 100% full refund of any money paid.
- Always cancel your policy using certified mail with a return receipt requested to establish legal proof of your cancellation date.
- Use this window to verify if your policy has a 2-year waiting period, which is standard for guaranteed issue burial insurance.
In this article
- What Is a Life Insurance Free Look Period?
- When Does the Free Look Clock Actually Start?
- How State Rules Protect You for 10 to 30 Days After Delivery
- 2026 State Free Look Mandates Comparison
- How Much Does Burial Insurance Cost in 2026?
- Average 2026 Monthly Premiums for $10,000 in Coverage
- Guaranteed Issue vs. Simplified Issue: What to Check
- What to Look for in Your Policy Packet Once It Arrives
- Your 5-Step Policy Review Checklist
- Common Red Flags to Watch for During Your Free Look Window
- How to Cancel and Receive a 100% Full Refund
- Can You Cancel Your Policy After the Free Look Period Ends?
- How Does Burial Insurance Differ from Medicare?
- How to Switch to a Lower Rate Without Risking Coverage
What Is a Life Insurance Free Look Period?
Buying life insurance is a major financial decision, and it is completely normal to feel a bit of buyer's remorse or uncertainty after signing the paperwork. That is exactly why the 30-day free look period exists. Think of it as a legally mandated test drive for your final expense insurance. It gives you a specific window of time to review your new policy, read the fine print, and decide if it truly meets your needs without risking a single penny.
According to the National Funeral Directors Association, the median cost of a funeral with a viewing and burial is around $8,300. Because funeral costs are so high, many seniors purchase burial insurance policies ranging from $10,000 to $15,000 to protect their families from unexpected debt. However, in the rush to secure coverage, you might agree to terms you do not fully understand. The free look period acts as a consumer protection safety net, ensuring you are never locked into a contract you do not want.
If you decide during this window that the policy is too expensive, the coverage amount is too low, or you simply changed your mind, you have the absolute legal right to cancel. When you cancel within the free look period, the insurance company is required by law to issue a 100% full refund of any premiums they have already drafted from your bank account. There are no cancellation fees, no penalties, and no questions asked.
When Does the Free Look Clock Actually Start?
One of the most common mistakes buyers make is misunderstanding when the free look countdown begins. Many people incorrectly assume the clock starts ticking on the day they sign the application, the day they speak to an agent on the phone, or the day their first premium payment is deducted from their bank account. This confusion can lead to missed deadlines and lost money.
In reality, the free look period begins on the exact date of policy delivery. This is the day you physically receive the printed policy contract in your mailbox, or the day you receive the official electronic document via email. The delivery date is the only date that matters when calculating your deadline.
Let us look at a real-world scenario to see how this works. Imagine you apply for a final expense policy on March 1. The insurance company approves your application on March 5 and drafts your first monthly premium on March 6. However, the physical policy packet does not arrive in your mailbox until March 15. Your 30-day free look period begins on March 15. You would have until April 14 to review the documents, cancel the policy, and get your money back.
If you opt for electronic delivery, the clock starts the moment the email containing your policy documents hits your inbox. Because email delivery is instant, your review window begins much sooner than it would with physical mail. Always save the envelope your policy arrived in or flag the delivery email, as these serve as your proof of the delivery date.
How State Rules Protect You for 10 to 30 Days After Delivery
While the National Association of Insurance Commissioners (NAIC) sets the baseline model regulations for consumer protections, it is your specific state's department of insurance that dictates the exact length of your free look period. Depending on where you live, your state will mandate a window of anywhere from 10 to 30 days.
In 2026, state regulators are paying closer attention to these laws than ever before. The NAIC is now strictly tracking the exact number of policies canceled by policyholders during the free look period. They use this data to identify insurance agencies that rely on deceptive or high-pressure sales tactics. If a specific agency has an unusually high number of free look cancellations, it triggers a regulatory red flag.
Different states have unique rules designed to protect vulnerable buyers, particularly seniors and those buying policies through the mail. For example, some states require a longer review period if you are replacing an old policy with a new one to prevent unethical agents from convincing you to switch just so they can earn a commission.
2026 State Free Look Mandates Comparison
| State Department of Insurance | Standard Free Look Period | Special Rules & Senior Protections |
|---|---|---|
| New York (NY DFS) | 10 Days | Mandates a strict 30-day free look period for any life insurance policy sold through the mail. |
| California (CA DOI) | 10 to 30 Days | Under SB 620, mandates a strict 30-day free look period for all individual life policies sold to seniors aged 65 and older. |
| North Carolina (NC DOI) | 10 Days | Requires a 10-day window for new policies, but extends this to 30 days if the consumer is replacing an existing policy. |
| Florida (FL OIR) | 14 Days | Provides a standard 14-day unconditional refund window from the date of policy delivery. |
Always check the front page of your policy document as soon as it arrives. State laws, such as California's AB 2347, require insurers to print the free look warning clearly on the front jacket of the policy so you know exactly how many days you have to make your final decision.
How Much Does Burial Insurance Cost in 2026?
During your free look period, you should carefully review your premium costs to ensure they fit comfortably within your fixed monthly budget. Burial insurance, which is a small whole life insurance policy, has premiums that are locked in for life. They will never increase as you get older, but your starting rate depends heavily on your age, gender, and health at the time you apply.
Based on 2026 data from MoneyGeek and LifeInsuranceInDepth, the average cost for a $10,000 final expense policy is roughly $30 per month for women and $38 per month for men. However, rates increase significantly as you age. In fact, premium costs roughly double between the ages of 60 and 75. Additionally, if you use tobacco products, you can expect your monthly cost to increase by 40% to 80% compared to a non-smoker.
Average 2026 Monthly Premiums for $10,000 in Coverage
| Age at Application | Average Monthly Cost (Female) | Average Monthly Cost (Male) |
|---|---|---|
| Age 50 | $24.24 | $30.55 |
| Age 60 | $46.00 | $60.00 |
| Age 70 | $84.00 | $110.00 |
| Age 80 | $168.00 | $222.00 |
If you receive your policy and realize the monthly draft will strain your budget, use your free look window to cancel. You can then review the true cost of final expense insurance and shop for a lower coverage amount, such as $5,000 or $7,000, which will come with a much more manageable monthly payment.
Guaranteed Issue vs. Simplified Issue: What to Check
One of the most critical details to verify during your free look period is the type of policy you actually bought. Final expense insurance generally falls into two categories: simplified issue and guaranteed issue. Mixing these up is a common source of buyer remorse, and discovering the difference early can save your family from a massive financial shock later.
Simplified issue policies require you to answer a few basic health questions on the application, but they do not require a medical exam. If you are approved, your coverage begins on day one. If you pass away a week after the policy is issued, your family receives the full $10,000 death benefit.
Guaranteed issue policies, on the other hand, ask zero health questions. You cannot be turned down for medical reasons. However, this guaranteed acceptance comes with a strict 2-year waiting period for burial insurance. This is known in the industry as a graded death benefit.
If you have a guaranteed issue policy and die of natural causes within the first two years, the policy will not pay the full face amount. Instead, it pays a refund of the premiums you have paid into the policy, plus interest (typically 10%). For example, if you paid $50 a month for 10 months and passed away from a heart attack, your family would receive your $500 back, plus $50 in interest, for a total of $550. They would not receive the $10,000 face value. Use your free look window to read the fine print and confirm whether your policy covers you from day one or if you have a waiting period.
What to Look for in Your Policy Packet Once It Arrives
When that thick envelope arrives in the mail, it can be tempting to file it away in a drawer without reading it. Do not make this mistake. The 30-day free look period is your only chance to catch errors and fix them without penalty. Set aside 15 minutes to sit down at your table, open the packet, and review the documents carefully.
You do not need to be a lawyer to understand your policy. You just need to verify that the promises the agent made on the phone match the legal contract printed on the paper. If anything looks incorrect, you can use your free look right to demand a correction or cancel entirely.
Your 5-Step Policy Review Checklist
- Verify the Free Look Clause: Look at the very front jacket of the policy. State laws require the free look period (10, 14, 20, or 30 days) to be printed clearly on the first page.
- Check Your Personal Details: Ensure your name is spelled correctly, your date of birth is accurate, and your address is correct. A misspelled name can delay a payout to your family.
- Confirm the Premium Amount: Look at the schedule of benefits. Does the monthly premium match what you were quoted? Verify that the contract explicitly states the premium is locked and will never increase.
- Review the Beneficiaries: Check the names of your primary and contingent beneficiaries. Make sure the money is going exactly where you want it to go.
- Look for the Waiting Period: Scan the first few pages for the words graded death benefit or limited benefit period. If you see this, you have a 2-year waiting period.
Common Red Flags to Watch for During Your Free Look Window
The free look period is designed to protect you from bad business practices. While most insurance agents are honest professionals, there are always a few bad apples who use aggressive or deceptive tactics to close a sale. If you spot any of these red flags while reviewing your paperwork, it is time to exercise your right to cancel.
The first major red flag is known as churning. This happens when an agent convinces you to cancel a perfectly good, older life insurance policy to buy a new one, simply so they can earn a new sales commission. If you recently replaced a policy and realize your new one is more expensive or has a new 2-year waiting period, use your free look window to cancel the new policy immediately. Many states offer a full 30 days specifically to protect seniors from churning.
Another serious red flag is incorrect medical information. Sometimes, an unethical agent will check no on health questions when you specifically told them yes, just to push your application through underwriting. If you look at the copy of your application attached to the back of your policy and see false health answers, cancel the policy. If you die and the insurance company discovers you had a pre-existing condition that was not disclosed, they can deny the claim entirely, leaving your family with nothing.
Finally, be wary of aggressive state-regulated final expense mailers that promise government benefits but actually sell private insurance. If the policy you receive looks nothing like the official government program you thought you were signing up for, cancel it immediately.
How to Cancel and Receive a 100% Full Refund
If you decide that the policy is not right for you, canceling during the free look period is a straightforward process, but you must follow the rules exactly to guarantee your 100% refund. A simple phone call to your agent is rarely enough to legally terminate the contract. You must create a paper trail.
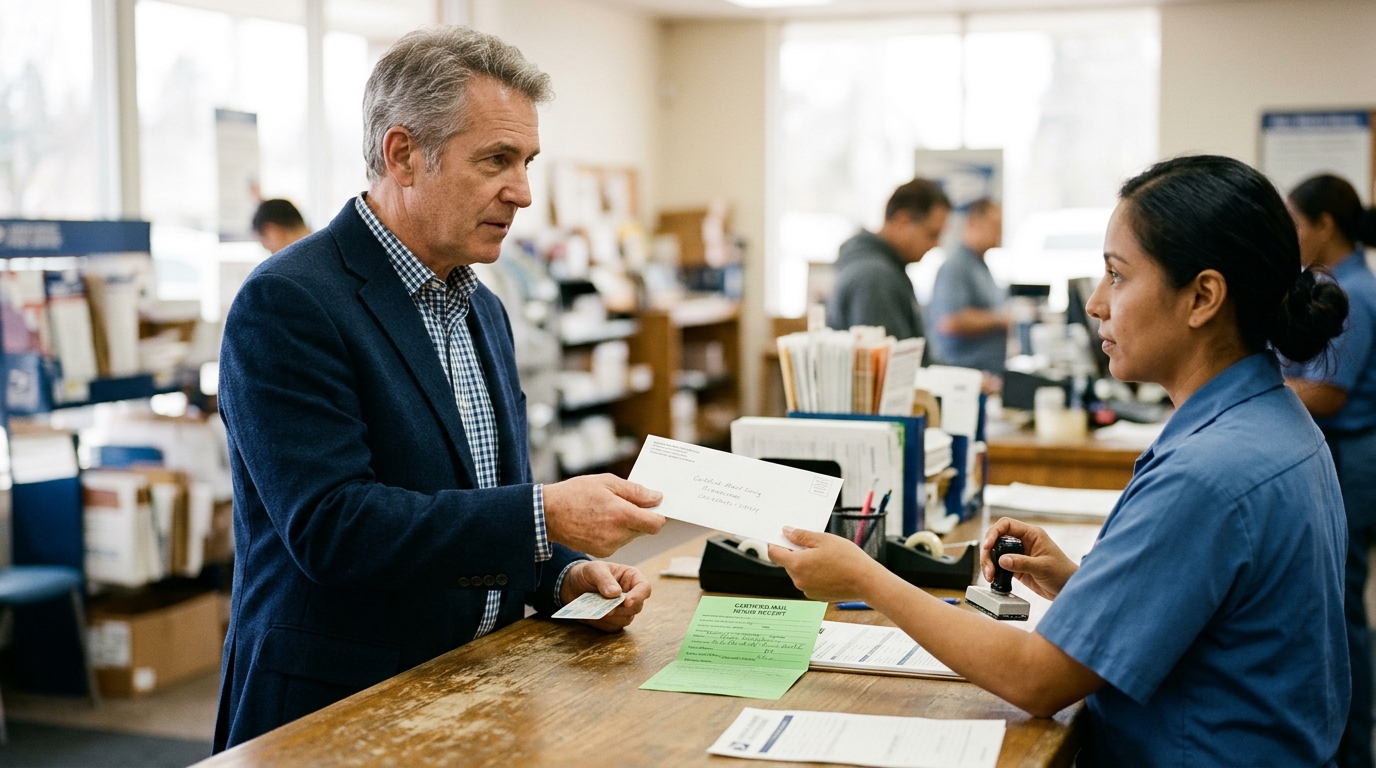
State insurance departments, including those in New York and Florida, highly recommend canceling your policy in writing. The most secure way to do this is by sending a formal cancellation letter via certified mail with a return receipt requested. This provides you with absolute legal proof of the exact date you mailed the cancellation, ensuring the insurance company cannot claim you missed the deadline.
Here is the step-by-step process to cancel safely:
- Read the Cancellation Instructions: Look at the free look clause on the front page of your policy. It will tell you exactly where to mail your cancellation notice. It is usually the insurance company's home office, not your local agent's office.
- Write a Brief Letter: You do not need to explain why you are canceling. Simply write, I am exercising my right under the free look period to cancel policy number [Insert Number]. I request a full refund of all premiums paid. Sign and date the letter.
- Mail It Certified: Take the letter and the original policy documents to the post office. Send them via certified mail with a return receipt. Keep the green receipt slip for your records.
- Monitor Your Bank Account: Once the company receives your notice, they are legally required to refund your initial premium. Watch your checking account over the next 10 to 14 days to ensure the money is deposited back into your account.
Can You Cancel Your Policy After the Free Look Period Ends?
A common question from buyers is what happens if they miss the 10 to 30 day window. Can you still cancel your policy later? The short answer is yes, you can cancel a life insurance policy at any time. You are never legally forced to keep paying premiums. However, the financial consequences change dramatically once the free look period expires.
If you cancel after the free look window has closed, you forfeit the 100% refund guarantee. The insurance company will keep all the premiums you have paid up to that point. Because burial insurance is a form of whole life insurance, it does eventually build up a small amount of cash surrender value. However, this cash value typically takes three to five years to accumulate.
If you cancel in year one or year two, you will likely walk away with nothing. If you cancel in year ten, you might receive a small check for the accrued cash value, but it will be significantly less than the total amount of premiums you paid in over the decade. This is why the initial 30-day window is so vital; it is your only chance to walk away completely whole.
How Does Burial Insurance Differ from Medicare?
Because final expense insurance is marketed heavily to seniors aged 65 and older, it is frequently confused with federal health programs. Many seniors mistakenly believe that burial insurance operates under the same strict rules as Medicare, but this is entirely false. Final expense is a private whole life insurance product, not a government health program.
This distinction is incredibly important for your shopping timeline. With Medicare, you are restricted to specific enrollment windows, and if you miss them, you face lifetime late enrollment penalties. Final expense has absolutely no open enrollment period. You can buy a policy, use your free look period to cancel it, and buy a different policy in January, July, or November. There are no federal deadlines and no late enrollment penalties for waiting.
Additionally, burial insurance has no deductibles, no copays, and no network restrictions. The death benefit is paid in tax-free cash directly to your chosen beneficiary, who can use it with any funeral home they choose. If you are wondering if Medicare covers funeral costs, the plain truth is that it does not pay a single dime toward burial or cremation, making private final expense insurance a necessary purchase for many families.
How to Switch to a Lower Rate Without Risking Coverage
If you are currently in your 30-day free look period and feeling unsure about your policy, do not panic. You have the legal right and the time to explore better options without risking your hard-earned money. The smartest move is to compare rates from other top-rated carriers before you officially mail in your cancellation letter.
At Rebel Rates, we believe in complete transparency. We provide you with the tools to see real prices from multiple carriers side-by-side, without the pressure of a pushy sales agent breathing down your neck. If you find a policy with a lower monthly premium or day-one coverage instead of a 2-year waiting period, you can secure the new policy first, and then confidently use your free look right to cancel the old one.
Ready to see if you can get a better deal? Take control of your final expense planning today. Compare final expense quotes now to find the lowest rates and the best coverage for your family's future.
Frequently asked questions
Is final expense insurance the same as burial insurance?
Yes, final expense insurance and burial insurance are exactly the same thing. Both are simply marketing terms used by the insurance industry to describe small whole life insurance policies designed to cover end-of-life costs, typically ranging from $5,000 to $25,000.
How long does it take to get my refund after canceling?
Once the insurance company receives your formal cancellation request within the free look window, it typically takes 10 to 14 business days for the 100% full refund to be processed and deposited back into the bank account used for the initial premium draft.
Does the free look period apply to policies bought through the mail?
Yes, and consumer protections are often stronger for mail-order policies. For example, states like New York mandate a strict 30-day free look period for any life insurance policy sold through the mail, giving you extra time to review the documents without an agent present.
Sources
This article is for general information and isn’t financial, legal or medical advice. Plan availability, benefits and prices vary by location, age and insurer.